
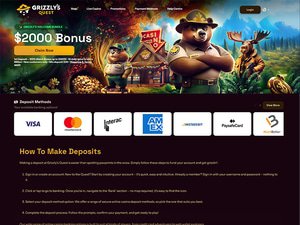
Choosing between Canadian casino banking options is less about counting logos and more about understanding how each method fits deposits, withdrawals, verification and provincial availability. The banking area described for grizzlys quest casino canada includes several familiar payment routes, but the exact selection can differ by account and location. A practical comparison should therefore focus on currency, ownership checks, withdrawal compatibility, fees and processing expectations rather than assuming every Canadian player sees the same cashier.
Which payment methods may appear in the cashier?
The reported cashier supports a range of familiar Canadian payment routes. Interac and Interac e-Transfer are especially relevant to local users, while Visa and Mastercard may suit people who prefer a conventional card. Digital-wallet choices can include Apple Pay and Google Pay, and some cashier configurations may also display bank transfer, INSTADEBIT, MuchBetter, Paysafecard or Flexepin.
These methods should not be treated as a guaranteed menu. Availability can depend on the account, province, currency selection and the operator’s current payment arrangements. A method shown for deposits may be unavailable for withdrawals, so the important comparison is not simply whether a logo appears. Check whether the same route supports both directions and whether the cashier identifies any method-specific conditions before committing funds.
Canadian-dollar accounts can make budgeting and record-keeping more straightforward because the balance is not necessarily exposed to an additional conversion step. Even so, the displayed currency does not establish that every method settles in Canadian dollars without charges. Banks, card issuers and payment providers can apply their own fees or exchange rates. Review the final confirmation screen and your provider’s terms before approving a transaction.
How should you compare deposits with withdrawals?
Deposits are usually the simpler side of the comparison. The available process involves opening the Bank or Cashier section, choosing a listed method, entering an amount and confirming the transaction. Card and electronic payments are generally described as being credited promptly, but that does not mean every deposit is instantaneous or that a pending transaction can never occur.
Withdrawals require more careful scrutiny. A deposit-only method may not be available for cashing out, and withdrawal minimums can differ by method or cashier configuration. Published reports identify different minimums, including figures around C$5, C$50 or other method-specific amounts. Because those reports are not consistent, the live cashier and current terms should take priority over any general figure.
Processing expectations also vary. Electronic methods may be handled within roughly 24 hours in some circumstances, while bank transfers and certain card payments can take several business days. That period may begin only after an internal review, rather than immediately when a request is submitted. Before depositing, identify the likely withdrawal route, minimum amount and any stated processing stage so that a convenient deposit method does not create an inconvenient exit.
What can delay a Canadian cashout?
Verification is one of the main conditions to consider. The account holder may be asked for government-issued identification, proof of address and evidence that the payment method belongs to them. Examples can include a passport or driver’s licence, a recent utility bill or bank statement, and a suitably masked card image or wallet record. The precise request can vary.
Information should match across the account and payment method. Differences in name, address or ownership details can lead to additional questions or a temporary hold while documents are reviewed. Completing registration does not necessarily mean every verification step is finished; an identity check may be requested before a first withdrawal or when the cashier triggers further review.
Bonus conditions can also affect a payout. The available terms describe a requirement to wager deposited funds once before withdrawal, with possible processing charges in some situations if money is removed without that step. Promotional balances may have separate wagering rules, and a cashout can affect pending promotional eligibility. For broader guidance on protecting payment information, consult Canada’s Financial Consumer Agency and apply the same caution to casino transactions.
When is a method convenient, and when is it restrictive?
Interac-based options may be attractive to users who already rely on Canadian banking services and want a familiar transfer path. Cards can be useful when the user values a widely recognized payment instrument, although card issuers may apply their own restrictions. Apple Pay and Google Pay can reduce the need to enter card details repeatedly, but their availability depends on device, account and cashier support.
Bank transfer can make sense for larger planned movements where a direct connection with a bank account matters more than speed. Its trade-off is that transfers may involve longer processing and a higher withdrawal threshold. Prepaid or voucher-style options such as Paysafecard or Flexepin can help separate a deposit from a primary bank card, but they may be deposit-focused and therefore unsuitable as a complete banking solution.
Digital wallets also deserve a specific check before use. A wallet can be convenient, yet the operator may require proof of wallet ownership or restrict it to certain transaction types. The best choice depends on the whole journey: funding the account, satisfying verification, requesting a withdrawal and receiving the money. A method that is fast for deposits but unavailable for payouts is not automatically the most practical option.
Which checks should be completed before choosing?
Start by opening the current cashier only after confirming that the account is eligible in the player’s province. The available source material indicates that service and promotions can differ across Canada, and Ontario residents may face separate restrictions. Geography alone does not establish access, so provincial eligibility and the applicable terms should be checked directly rather than inferred from a Canadian interface.
Then compare the details that affect the final cost and effort:
- Currency: confirm that the account and selected method use the intended currency.
- Direction: check whether the method supports both deposits and withdrawals.
- Minimums: review the current deposit and cashout thresholds.
- Timing: distinguish internal processing from the provider’s delivery time.
- Verification: prepare documents if ownership or identity checks are requested.
- Fees: look for operator, bank, card or payment-provider charges.
Finally, save transaction records and avoid using another person’s card or wallet. Keep the account name and payment ownership consistent, and do not assume a promotional deposit requirement is the same as the ordinary minimum. If the cashier displays a different option or condition, treat that live information as controlling and ask support for clarification before sending money.
Canadian casino banking options: frequently asked questions
Are all listed banking methods available to every player?
No. Payment availability can vary by province, account, currency, cashier configuration and transaction direction. A method may accept deposits but not withdrawals, or disappear after an account review. Check the live cashier and current terms rather than relying on a general list or another player’s experience.
Does a fast deposit guarantee a fast withdrawal?
No. Deposits and withdrawals can follow different approval processes, minimums and provider timelines. A withdrawal may also require identity or payment-ownership verification before processing. Electronic payments may be quicker in some cases, while bank transfers and certain card routes can take several business days.
What should be checked before using a payment card?
Confirm that the card is in the account holder’s name, the method supports withdrawals if needed, and any minimums or fees are acceptable. Keep transaction records and be ready to provide suitably masked ownership evidence. Also check whether the card issuer applies restrictions or additional charges to the transaction.